

Klover - Instant Cash Advance

- 51.93K Reviews
- 4.6
- Downloads
- 5,000,000+
Our take on Klover - Instant Cash Advance from Appgk
When an unexpected bill lands between paydays, Klover is designed to make the problem feel less overwhelming. I found it most useful as a short-term cash-flow tool rather than a general banking replacement: it focuses on helping eligible users access money quickly, while still requiring careful attention to repayment and personal budgeting. That distinction matters, because an instant advance can solve a timing problem without solving an income problem.
Klover is a free finance app from Klover Holdings, available for everyone and supported on Android devices running version 7.0 or later. It has built a sizeable audience, with more than five million installs, a 4.6 average from roughly 165 thousand ratings, and about 52 thousand written reviews. Those numbers suggest that the basic idea is resonating with many people, although popularity should never be confused with a guarantee that every user will receive an advance or find the terms suitable.
My overall view is straightforward: this is best treated as a backup tool for a temporary gap, not as money to rely on every pay cycle. If you need help covering a genuinely short delay and can comfortably manage the resulting deduction, Klover may be worth considering. If you are already using advances to cover recurring expenses, a slower and more structured alternative is likely healthier.
How the app feels in everyday use
The main experience is centered on requesting cash rather than managing a full checking account. That makes the app easier to understand than a broad personal-finance platform filled with investing, bill-pay, credit-monitoring, and banking sections. I can see the appeal for someone who opens an app with one urgent question: “Can I bridge this gap until my next income arrives?”
Best Parts of Klover - Instant Cash Advance
Things to Keep in Mind About Klover - Instant Cash Advance
The first practical step is setting up an account and completing the information needed for eligibility. This is where expectations should stay realistic. Seeing an app advertised around instant cash does not mean every applicant receives the same amount, receives it immediately, or qualifies each time. Eligibility can depend on information connected to the user’s financial situation, and the app should be approached as an assessment process rather than an automatic emergency fund.
I also recommend reading every screen before confirming a request. In a rushed situation, people tend to focus on the amount they want and tap through the rest. That is exactly when details about repayment timing, delivery speed, optional services, or account requirements deserve extra attention. A few minutes spent checking the final arrangement is more valuable than getting surprised later when money leaves the account.
News and Features Related to Klover - Instant Cash Advance

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
One useful habit is to decide the repayment plan before requesting anything. I would first write down the upcoming income date, essential bills, food and transport costs, and the amount that must remain untouched. Only after that would I consider whether an advance fits. This small workflow changes Klover from an impulse button into a controlled response to a temporary timing mismatch.
Where the experience is strongest
The app’s clearest strength is focus. It does not ask me to learn a complicated financial dashboard before reaching the service I came for. For a user facing a practical shortfall, that directness can reduce friction. The free download also lowers the barrier to trying the service, although free access to an app should not be interpreted as free money or as proof that every related option has no cost.
Don't want to read the full review?
Another strength is the way the product fits a specific kind of emergency: a bill is due now, but regular income is expected soon. Imagine a commuter whose car needs a repair before the next paycheck. If the person has a reliable income date and enough room in the following budget to absorb repayment, an advance could prevent missed work. That is a more sensible use than borrowing for a discretionary purchase that can simply wait.
I would also use the app as a planning checkpoint, not just a transaction screen. Before requesting money, I would compare the proposed advance with two alternatives: delaying a nonessential payment after contacting the provider, or using savings that are already earmarked for emergencies. Sometimes the best result from opening Klover is realizing that the advance is unnecessary once the full budget is visible.
Screenshots
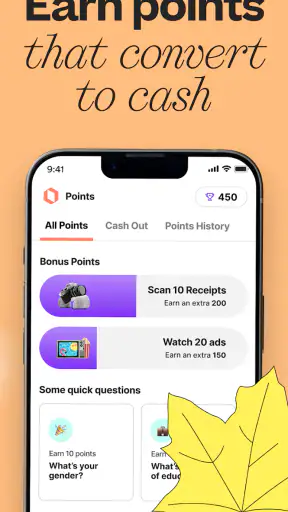
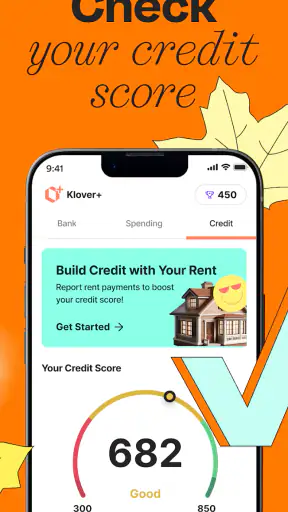
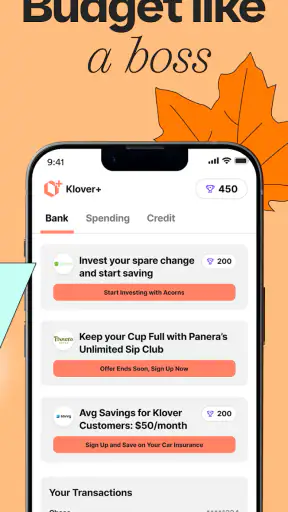
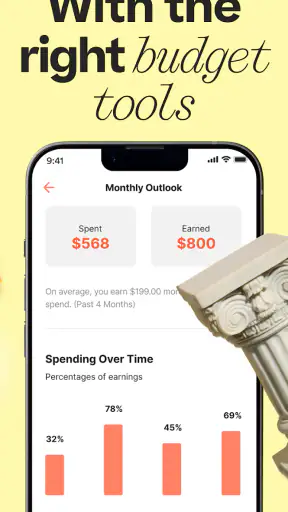
The app’s long presence in the finance category is another modest reassurance for people who prefer an established product over an unknown download. Klover Holdings released it in April 2020, and the current version is 2026.12.0. That continuing development indicates an actively maintained service, but it does not remove the need to review the current in-app terms each time. Financial products can change their eligibility checks, delivery choices, or repayment details as they evolve.
What I would check before requesting money
I would begin by confirming that the connected income and account information is accurate. Incorrect or outdated details can create unnecessary friction and may lead to an outcome that does not match expectations. If the app asks for access to financial information, I would read the explanation carefully and make sure I understand why that information is relevant to the service.
Next, I would look at the exact timing. “Instant” is an attractive word, but the practical arrival of funds can depend on the selected delivery method and the user’s financial institution. If the bill is due within hours, I would not assume that opening the app guarantees money in time. I would prepare a backup plan before relying on any advance for a deadline-sensitive payment.
I would then examine the repayment impact on the next pay period. The important question is not only whether the amount helps today, but whether the reduced balance later will leave enough for rent, utilities, groceries, transportation, and other essentials. A request that appears manageable in isolation can become expensive in practical terms if it causes another shortfall a week later.
Finally, I would save confirmation details and monitor the account afterward. This is a simple but often overlooked step. Knowing what was requested, when repayment is expected, and how much will remain afterward makes it easier to spot a problem early. It also discourages repeatedly taking advances without seeing the cumulative effect on the monthly budget.
The important weakness: convenience can hide a repeating cycle
The biggest limitation is not the interface; it is the temptation created by easy access. When a cash advance is only a few taps away, it can become a substitute for fixing a recurring mismatch between income and expenses. That is the point where convenience stops being helpful. If every payday begins with money already committed to an earlier advance, the app is no longer bridging an occasional gap; it is becoming part of the gap.
This is why I would not recommend Klover to someone whose essential expenses regularly exceed their income. An advance may postpone the pressure, but it cannot make rent, debt, or household costs permanently affordable. In that situation, speaking with creditors, reviewing recurring subscriptions, seeking a nonprofit budgeting service, or exploring a more structured financial solution may be more appropriate.
There is also a psychological cost to speed. A traditional bank loan, credit union conversation, or careful budget review creates time to consider the decision. An instant-cash app naturally encourages urgency. That is useful when the emergency is real, but risky when the purchase is optional or the user has not checked what repayment will do to the next budget.
I would be especially cautious about using it for entertainment, shopping, gifts, or other expenses that can wait. Borrowing against future income for a nonessential item turns a temporary convenience into a future obligation without protecting transportation, housing, health, or work. Klover makes the most sense when the timing problem is genuine and the repayment plan is already clear.
How it compares with familiar alternatives
Compared with a credit card, Klover may feel more targeted because its purpose is a short-term cash advance rather than an open-ended spending line. A credit card can be more flexible for purchases, but it can also encourage a balance to remain unpaid and accumulate costs. Klover’s focused design may help users think in terms of a specific gap, although the exact arrangement still needs to be reviewed carefully.
Compared with an overdraft, an advance can be preferable when the user knows an expense is coming and wants to avoid a failed payment. However, the right choice depends on timing, eligibility, and the consequences attached to each option. I would not assume that one is automatically cheaper or faster. I would compare the actual terms and the date money must be available rather than choosing based on the label alone.
A credit union or personal loan can be a better fit for a larger, planned expense because those options may offer a more deliberate repayment structure. They also take more effort and may not solve an emergency that needs attention today. Klover occupies the narrow space between a full loan application and simply waiting for income, which is useful precisely because it is limited.
Savings remain the strongest alternative when they are available and using them will not endanger another emergency. There is no repayment deduction after the fact, and the decision is easier to evaluate. Still, many people do not have enough accessible savings, which explains the appeal of a cash advance. My advice is to compare the advance with available savings honestly, instead of protecting a savings balance at all costs while creating a more difficult obligation.
Who is most likely to benefit
I think Klover suits an adult with predictable income, a temporary timing issue, and enough discipline to calculate the next budget before requesting money. It can be practical for a necessary expense that cannot wait until payday, especially when the user already knows exactly how repayment will fit into the following income cycle.
It may also help someone who wants a simple, focused finance app rather than a large platform with many unrelated tools. The clean purpose is easier to explain to a friend: use it to investigate whether a short-term advance is available, then decide based on the repayment effect. That clarity is more valuable than a long list of features for a person dealing with one immediate problem.
I would tell a potential user to skip it if income is irregular and there is no dependable date for money to arrive. I would also suggest looking elsewhere if the requested amount would cover recurring necessities month after month, because that pattern signals a broader budget issue. Someone seeking long-term credit building, detailed spending analysis, or a full banking relationship may find a bank, credit union, or dedicated budgeting application more suitable.
The age rating of Everyone makes the app broadly accessible in store terms, but financial responsibility is still an adult concern. Younger users and anyone unfamiliar with borrowing should involve a trusted adult or financial counselor before accepting an advance. Accessibility should not be mistaken for simplicity of consequences.
Small habits that make the app safer to use
- Set a personal limit before opening the request screen. Decide what amount would solve the immediate problem without putting essential expenses at risk.
- Check the arrival timing against the actual bill deadline, and keep another payment plan ready if the deadline cannot move.
- Review the next income cycle as a complete budget, not just as a payday balance. Include automatic payments and irregular essentials.
- Use an advance for a defined, one-time need rather than combining several optional purchases into one request.
- After repayment, note what caused the shortfall. A recurring transport, medical, or utility problem may need a permanent adjustment instead.
These habits are not extra decoration around the app; they determine whether the service remains a useful bridge or becomes a repeating dependency. The technology can make the request convenient, but the user still has to decide whether the underlying trade-off is sound.
My final recommendation
After looking at Klover as a finance tool rather than a quick fix, I see a product with a clear and useful role. It is free to install, has broad device support, and comes from Klover Holdings, a developer with an app that has been available since 2020. Its strong store reception and large install base make it easy to understand why people consider it when money is tight.
My recommendation is conditional but positive: consider it for a genuine, short-lived cash-flow problem when your income is dependable and you have already checked the repayment effect. Do not treat the availability of an advance as evidence that you can afford the expense. The most important question is whether the next budget remains stable after the money is received.
Klover is a reasonable emergency bridge, but it is not a replacement for savings, income, or a sustainable spending plan. If that boundary is clear, the app can be useful and straightforward. If the same shortfall keeps returning, I would choose a more structured solution and use this kind of advance only as an exceptional measure.
Klover - Instant Cash Advance FAQ
What is Klover - Instant Cash Advance, and how does it work?
Klover is a financial app designed to give eligible users access to small cash advances before their next paycheck. After creating an account, you typically connect a qualifying bank account and allow Klover to review income and account activity. If approved, the available advance and delivery options are shown in the app. It is not a replacement for regular income or a long-term lending solution.
How much money can I get through Klover?
The amount available through Klover depends on your eligibility, income patterns, account history, and other information verified by the service. New users may receive a smaller limit, while consistent account activity can affect future offers. The app displays the amount you qualify for before you confirm a request. Limits, eligibility rules, and availability can change, so users should review the current terms carefully.
Does Klover charge fees or interest for cash advances?
Klover’s costs depend on the advance and delivery method you choose. Some standard options may be available without traditional interest, while faster delivery or optional features can involve fees. Because pricing and product terms may vary by user and location, do not assume every advance is free. Before accepting money, check the in-app disclosure for the total cost, timing, and any optional charges.
How quickly does Klover send the money?
Delivery speed depends on the option selected, your bank, account verification, and whether your request passes Klover’s review. Standard transfers may take longer, while an instant option may be available for an additional fee and may not work with every bank. The estimated arrival time should appear before confirmation, but weekends, holidays, verification issues, or banking delays can affect when funds become available.
Is Klover safe to use, and what information does it require?
Klover requires personal and financial information to determine eligibility and support its services. You may need to provide identity details and securely connect a bank account that meets its requirements. As with any financial app, download it only from an official app store, review permissions and privacy disclosures, and use a strong password. Never share login codes or sensitive account information with unsolicited callers or messages.











